Climate change has changed the way countries view energy, industry, and economic security. If in the 20th century petroleum became a strategic commodity that determined the strength of the country, then in the 21st century the position began to be occupied by critical minerals such as nickel, lithium, cobalt, copper, and rare earth elements.
These minerals are the main components in electric vehicles, batteries, and the semiconductor industry. As a result, the global energy transition to a low-carbon economy creates not only technological competition, but also competition for control of critical minerals supply chains.
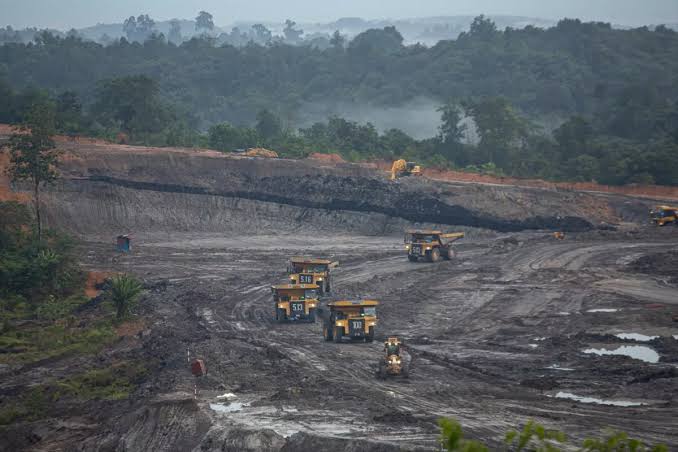
In the Indo-Pacific region, apart from China, Indonesia and Australia emerged as two countries that have strategic positions in the supply chain. Indonesia is the world’s largest nickel producer and has large reserves of copper, tin, and other important minerals.
Meanwhile, Australia is one of the world’s largest lithium producers and has significant rare earth reserves. The combination of the two countries’ resources makes them important actors in the global energy transition agenda. At the same time, the geopolitical dynamics between the United States and China gave birth to a phenomenon known as the China Plus One Strategy.
This strategy encourages global companies to diversify their supply chains to be less dependent on China. The COVID-19 pandemic, the US-China trade war, and Beijing’s restrictions on the export of some strategic minerals have raised concerns about the concentration of global supply chains in one country.
Read More: Trump, Australia’s PM Sign Critical Minerals Deal as China Dominates the Industry
Climate change has prompted countries to accelerate the transition to clean energy. The net zero emission targets adopted by various countries have caused the demand for electric vehicles and renewable energy technology to increase significantly.
As a result, the demand for critical minerals is also increasing. Minerals such as nickel and lithium are now strategic commodities that determine the success of the global energy transition. In this context, Indonesia and Australia have complementary characteristics.
Indonesia controls most of the world’s nickel supply, while Australia has an advantage in lithium production and the development of modern mining technology. Thus, climate change indirectly creates incentives for both countries to deepen economic and technological cooperation.
One of the most important developments in Indonesia-Australia relations is the growing concern for critical minerals. Indonesia has now down-streamed nickel through a ban on raw ore exports and the construction of domestic processing facilities. This policy makes Indonesia a dominant player in the global battery supply chain.
On the other hand, Australia is trying to strengthen its position as a supplier of lithium and rare earths to Western countries. Canberra is also increasingly active in various international initiatives to reduce the dependence of critical minerals supply chains on China.
Cooperation between the two countries becomes logical because each has different but complementary advantages. Indonesia needs technology, investment, and market access. Australia needs industrial partners who are able or willing to process minerals into value-added products and also have an important position in the global supply chain.
Therefore, Indonesia-Australia relations in the critical minerals sector have the potential to develop from mere commodity trade to the development of an integrated industrial supply chain.
China Plus One and Emerging Opportunities
The China Plus One phenomenon provides additional momentum for cooperation between the two countries. Over the past two decades, China has managed to establish an extraordinary dominance in the processing of critical minerals.
China has shown a lot that it is not just because of its mineral reserves, but because of its processing capacity, long-term investment, and strong industrial integration. But the growing geopolitical rivalry is prompting Western companies to look for alternatives outside of China. They don’t want to completely exit the Chinese market, but they want to reduce the risk of dependency.
In this situation, Indonesia and Australia offer an interesting combination. Australia can provide and have an advantage in lithium, rare earths, its mining technology, and funding and market access to developed countries. While Indonesia can provide and have advantages in nickel, its manufacturing base, and also its important position in the global supply chain.
Cooperation will not develop on its own and will not happen automatically. A mechanism is needed that can reduce the risk of uncertainty. First, both countries need to build an integrated critical minerals supply chain. The focus of cooperation should not stop at the mineral extraction stage, but should include processing, battery manufacturing, and recycling. Second, there needs to be an increase in technology transfer.
Read More: The Shift in Global Power as Rare Earth Minerals Become the New Oil
Australia has a long experience in sustainable mine management, while Indonesia has a growing market and industrial capacity. Research cooperation between universities and industry can be an effective means of knowledge transfer.
Third, the two countries need to develop environmental standards together. One of the main challenges in building the nickel industry in Indonesia is criticism related to environmental impacts and the use of coal-based energy in the processing process.
Therefore, Indonesia’s green industry needs to pay attention to improving environmental standards and its governance that emphasizes sustainability.
Fourth, Indonesia and Australia need to establish a permanent forum on critical minerals and energy transition. The forum can serve as a forum for coordinating investment policies, research, and supply chain security, as well as increasing transparency to the public.
Leverage IA-CEPA, critical minerals cooperation memorandums, and Indo-Pacific regional forums to serve as mechanisms that reduce uncertainty and strengthen policy coordination. From this, Indonesia gained added value to industry and jobs, while Australia gained a wider market and a stronger position in the global energy supply chain.
This cooperation is not only driven by economic interests, but also by the shared need to create a more resilient supply chain amid increasing global geopolitical rivalry. Therefore, the future of Indonesia-Australia relations is likely to be increasingly determined by the two countries’ ability to build strategic partnerships in the critical minerals sector and energy transition.
*The views presented in this article are the author’s own and do not necessarily reflect the views of The Diplomatic Insight.*